
What is a car insurance deductible?
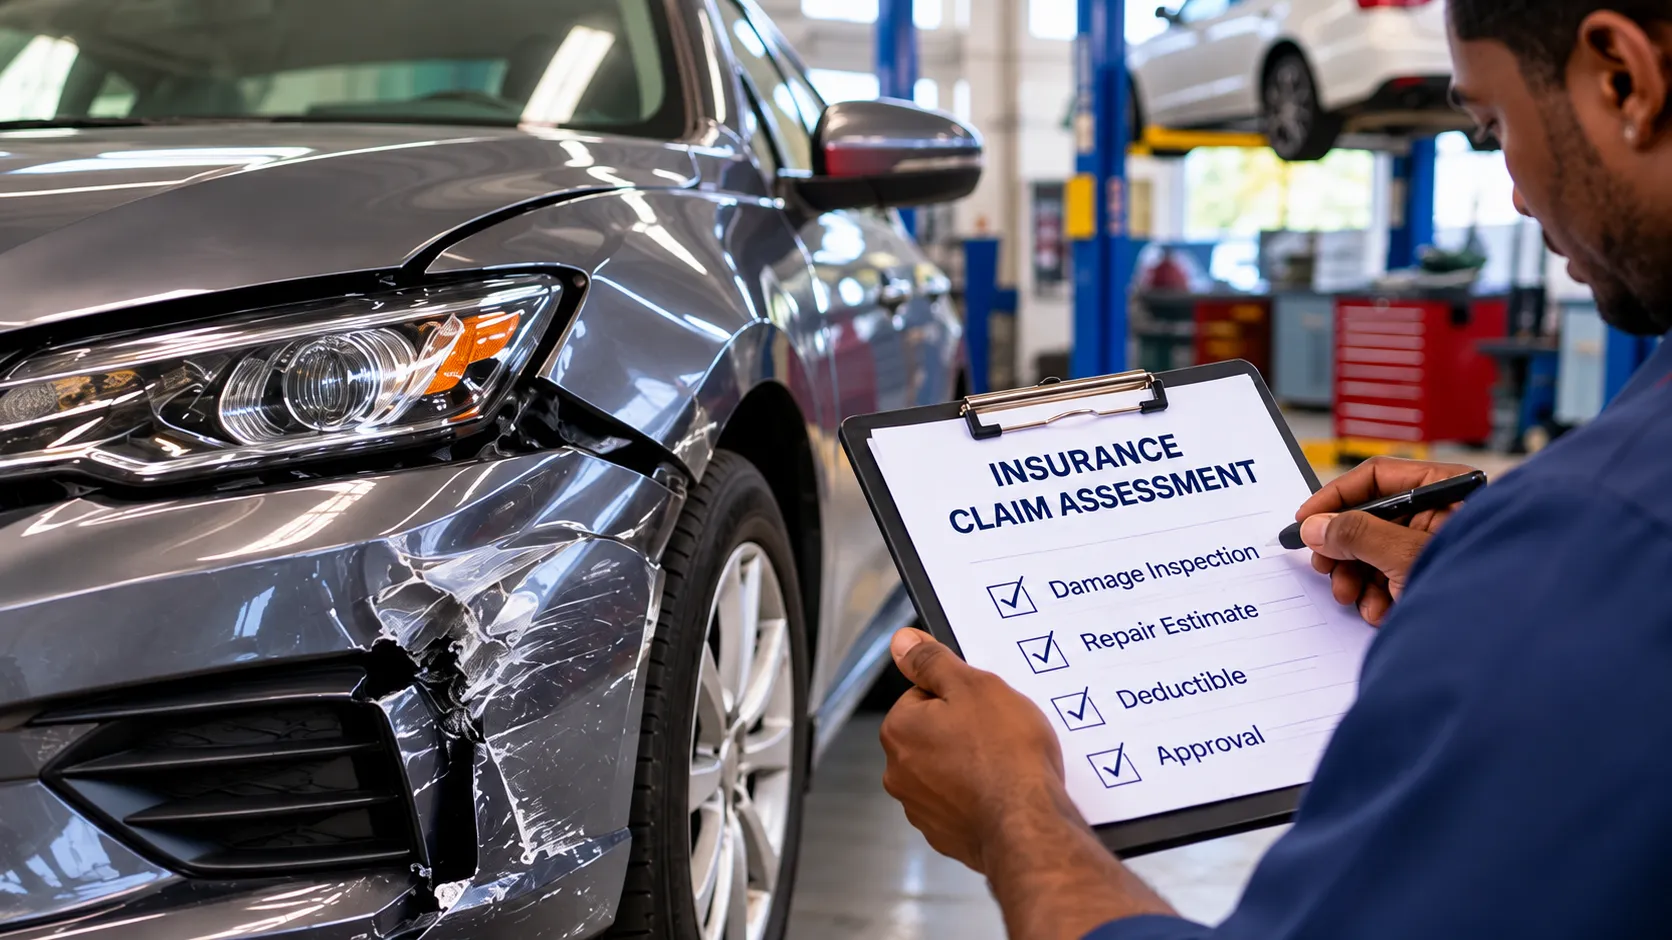
A deductible is an amount the policyholder may pay toward a covered loss before the insurer pays the remaining covered amount, subject to the policy’s terms and limits. It is a cost-sharing feature, not a penalty and not a coverage limit. A limit is generally the maximum amount the insurer may pay for a covered loss under a coverage; a deductible is generally subtracted from a covered loss before payment.
For example, a policy might have a $500 deductible and a separate coverage limit or boundary. On a covered $2,000 repair, the deductible can reduce the insurer’s payment before other policy terms are applied. The deductible describes the portion retained by the policyholder; a limit helps define the insurer’s potential payment. Actual claim results still depend on the coverage, facts, exclusions, and policy wording.
Many drivers encounter deductibles with physical-damage coverage, including collision and comprehensive. Do not assume every coverage has one. Liability coverage, for example, serves a different purpose and policy terms determine whether any deductible applies. For a foundation on that protection, see what liability insurance covers.
Collision and comprehensive commonly have deductibles because they can address damage to the insured vehicle. Liability coverage generally does not use a deductible paid by the insured in the same way when it addresses covered claims against the driver. Policy structures can vary, so check the declarations page for the deductible attached to each coverage.
How does a deductible work?
Suppose a covered repair is $2,000 and the applicable deductible is $500. If the policy applies as expected and no other condition changes the result, the insurer may pay $1,500 and the policyholder may be responsible for $500. If the covered repair amount is below the deductible, the insurer may pay nothing for that portion of the loss.
This is only an illustration. Actual claim handling can depend on the cause of loss, covered damage, exclusions, repair estimate, limit, policy language, and state law. Read the declarations page and policy rather than assuming a deductible works identically on every claim.
If a covered repair estimate is $400 and the applicable deductible is $500, there may be no insurer payment for that vehicle damage under that coverage because the amount does not exceed the deductible. That does not decide every claim or every cost; it illustrates why the deductible belongs beside the premium when comparing coverage.
Collision and comprehensive deductibles
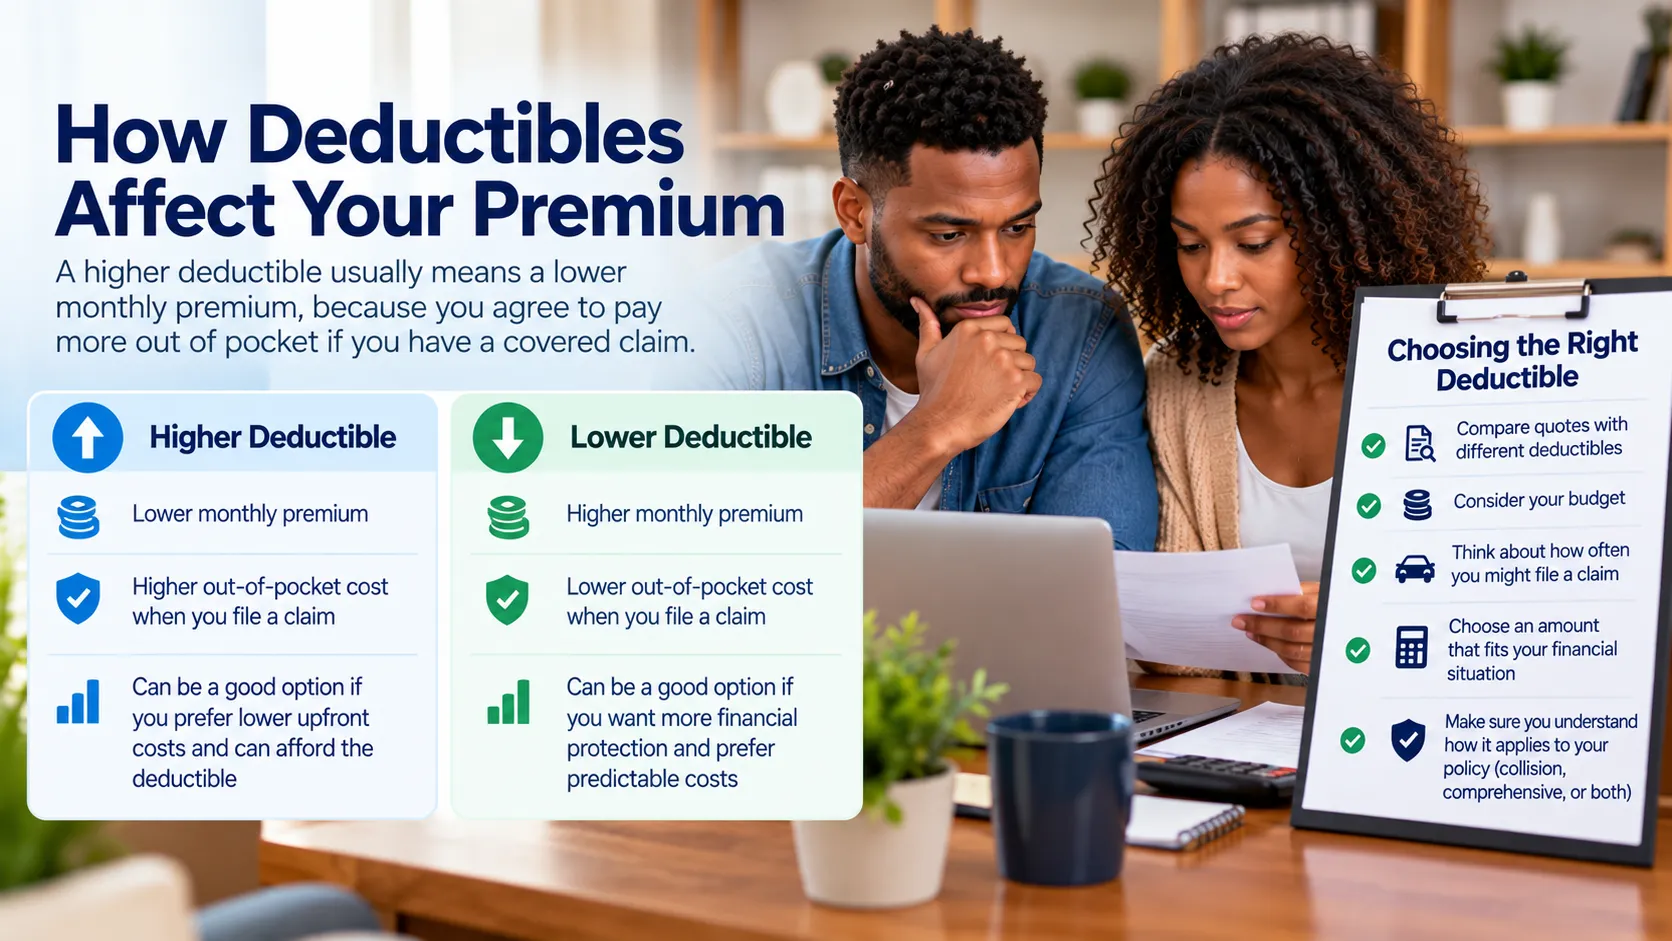
Collision coverage generally concerns covered damage from an impact with another vehicle or object. Comprehensive coverage generally concerns certain non-collision losses, such as theft, fire, weather, vandalism, or animal strikes. A policy can have collision, comprehensive, both, or neither, and it can set separate deductibles for each.
A quote might show a $1,000 collision deductible and a $500 comprehensive deductible. That does not mean every insurer offers those choices or that they fit every vehicle. Available levels can depend on the insurer, policy, coverage, vehicle, and state. Compare the selections actually shown rather than assuming both coverages share one amount.
Check each amount separately. Choosing a $500 collision deductible does not establish the comprehensive deductible, and a glass-related claim may be treated under specific policy or state rules. Comprehensive versus collision explains why the labels should not be treated as interchangeable.
When does a deductible apply?
A deductible generally applies only when the relevant coverage applies to a covered loss. The loss must fit the policy, and exclusions, limits, conditions, or another party’s insurance can affect the result. Ask the insurer which deductible applies to each coverage shown on the declarations page and whether any endorsement changes it.
The informal phrase “full coverage” does not answer that question. It is not a standardized policy package. A policy described that way can still have different collision and comprehensive deductibles, exclusions, limits, and optional benefits. See what full coverage means for the limits of the term.
Do you pay a deductible if you are not at fault?
Not necessarily—but do not assume an at-fault finding automatically eliminates a deductible. If you use your own collision or comprehensive coverage, its deductible may apply under your policy while responsibility is investigated. Depending on the facts, state rules, policy terms, and recovery from another party, an insurer may pursue subrogation and a deductible may sometimes be recoverable. Neither recovery nor its timing is guaranteed.
The answer can depend on which coverage is used, which insurer handles damage initially, fault determination, the other party’s insurance, state rules, and whether recovery succeeds. An insurer may seek recovery from a responsible party or insurer through subrogation; deductible reimbursement can sometimes follow. It is not a promise that reimbursement will occur.
Keep claim records, estimates, photographs, and communications, and ask the insurer how it will handle the deductible under the policy. The other driver’s liability coverage, fault determination, coverage availability, and applicable law can all matter.
$500 vs. $1,000 deductible
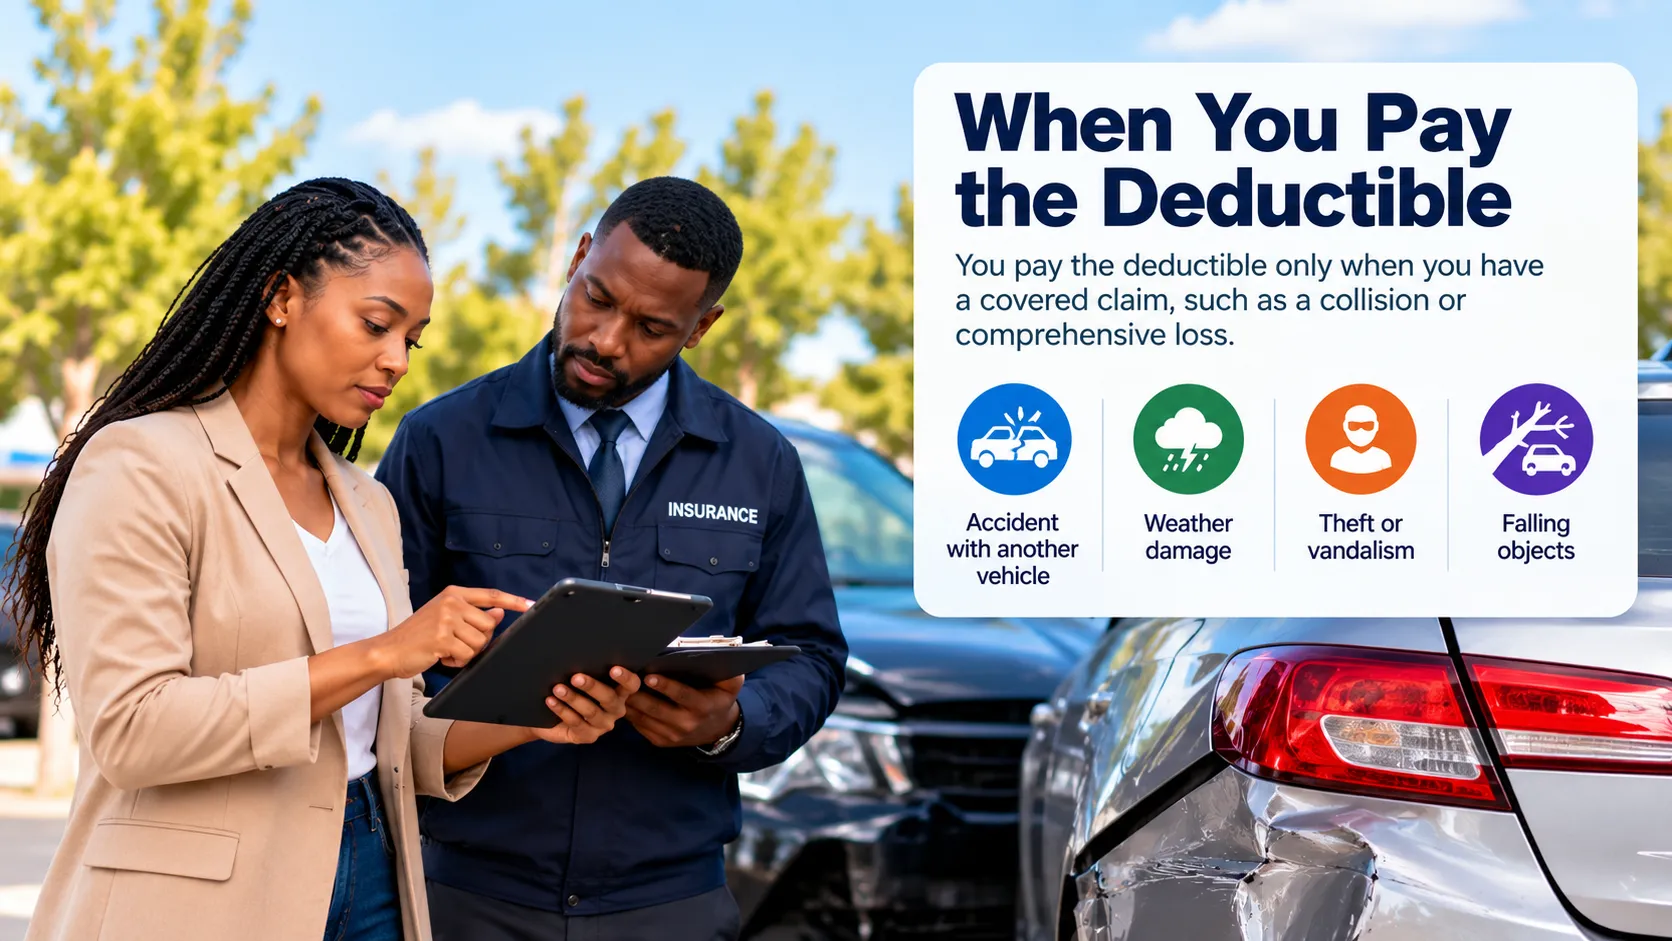
A $500 and $1,000 deductible represent different out-of-pocket amounts after a covered loss. A higher deductible can generally reduce premium, but it also means retaining more of the repair cost. The premium difference is not fixed across insurers, vehicles, coverage selections, or states.
There is no universal best deductible. Consider whether you could manage the higher amount when a covered repair is needed, the actual premium difference, the vehicle’s value, and other financial obligations. Do not select an amount solely because another driver uses it. Car insurance cost and ways to examine insurance costs can help frame the tradeoff without treating less protection as an automatic answer.
How deductibles affect a quote
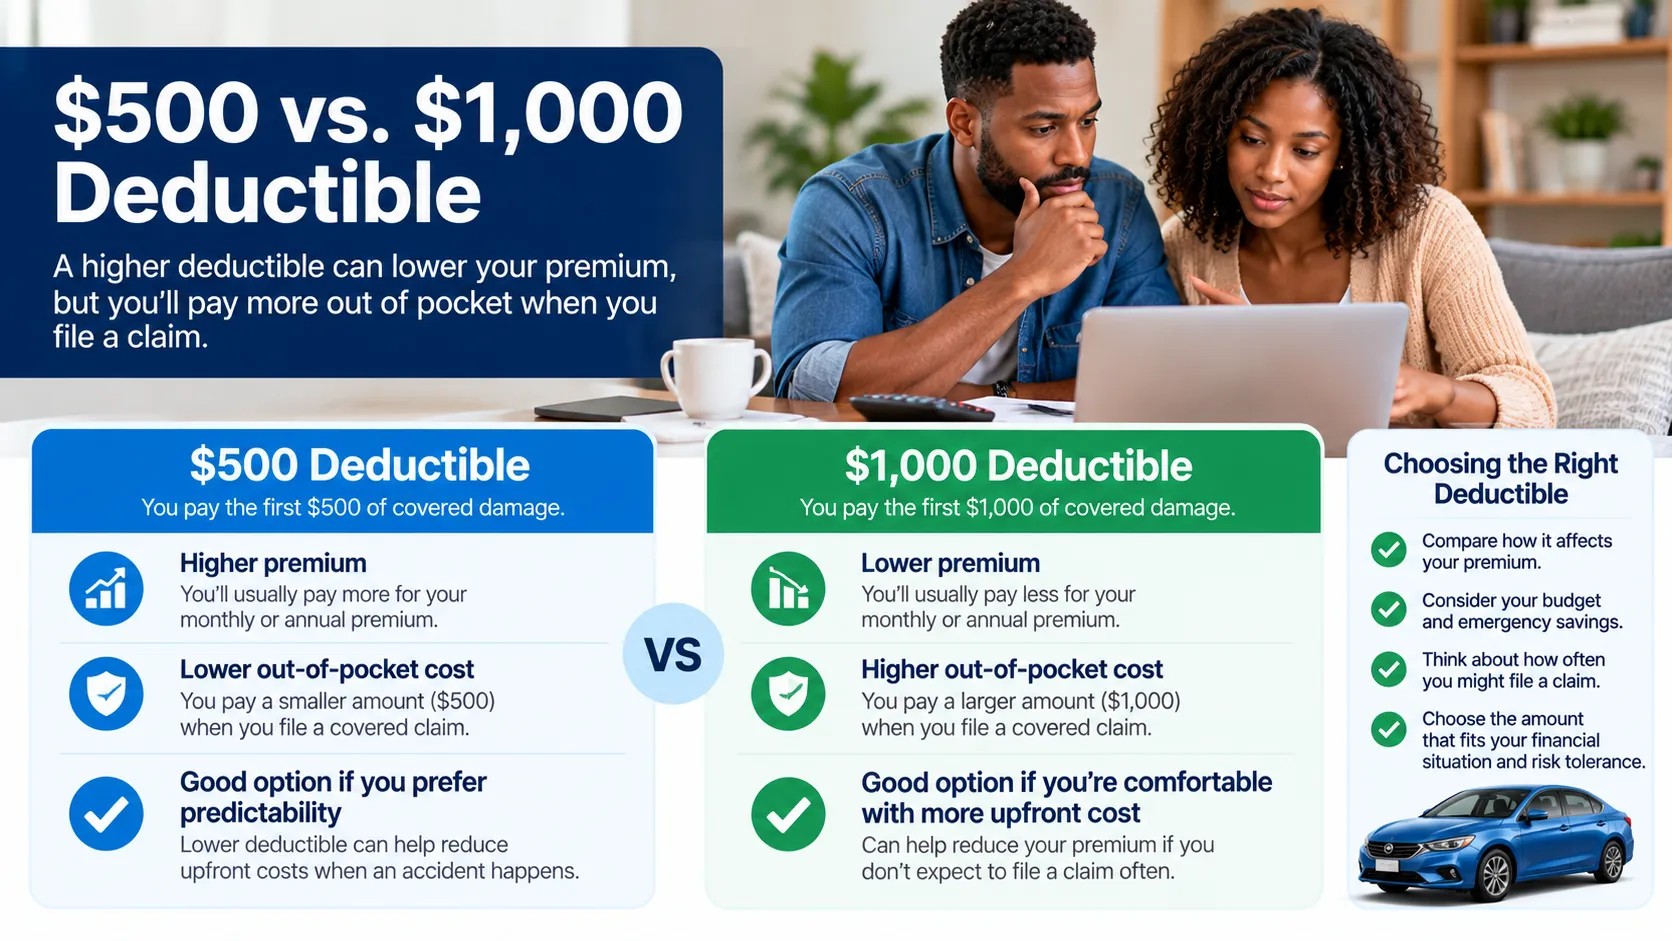
When comparing quotes, match the collision and comprehensive deductibles before comparing premium. A lower premium can reflect a higher deductible, less coverage, a different term, or different rating assumptions rather than better pricing for the same policy. Record the full premium, effective dates, payment plan, and deductible for every quote.
Use the car insurance quote comparison guide to line up limits, optional coverages, and fees as well. The useful question is what changes in both the premium and the amount you may need after a covered loss.
Financed and leased vehicles
A lender or lessor may require collision and comprehensive coverage and may set conditions about deductibles. Those are contractual requirements, separate from state-required insurance. Read the loan or lease agreement, give the insurer correct lender information, and confirm the issued policy meets the agreement’s requirements.
Deductible checklist
- Identify which coverages on the declarations page have deductibles.
- Record collision and comprehensive deductibles separately.
- Ask which deductible applies to the kind of loss you are considering.
- Compare equal deductibles when comparing premiums.
- Check lender or lease requirements, if applicable.
- Keep claim records and ask the insurer about recovery rather than assuming reimbursement.
Bottom line
A deductible is the portion you may pay toward a covered loss before your insurer pays its covered share. It differs from a coverage limit, may apply differently by coverage, and can affect premium and out-of-pocket risk. Use the actual policy, quote, and state-specific information to understand the deductible that applies.